COP31: investors call for repricing emerging market transition risk
Investors at COP31, including Impact Fund Denmark's Søren Peter Andreasen and PKA's Inger Huus-Pedersen, argued that emerging market transition assets are penalised for perceived rather than real risk
Capital flows often lag investor interest in emerging market (EM) transition assets. For instance, despite optimistic rhetoric Britain’s pension funds invest at most a tenth of their portfolios in EM listed assets.
At COP31, investors backed the call to expand EM exposure – driven by growing attractiveness of transition assets. Crucially, they also called for repricing transition risk in EMs, which they viewed as unjustifiably high.
Longview Networks Insurance Investment Forum | 20th January 2027 | London
Emerging appetite
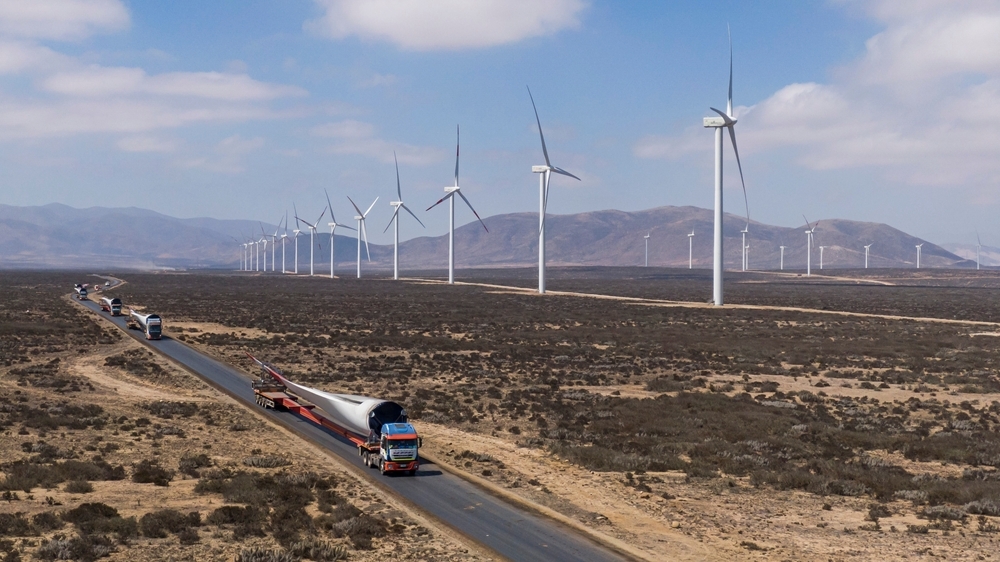
Amongst the investors on the ground in Antalya was Denmark’s Impact Fund. The sovereign backed investor recently closed a €650m EM growth fund anchored by five of the country’s largest pension schemes. Its portfolio includes companies such as Radiance, an Indian renewable energy platform operator.
Speaking at a COP31 side event, Impact Fund Denmark’s chief executive Søren Peter Andreasen stressed the attractiveness of EM transition assets. “Green business opportunities are getting more attractive from a commercial perspective”, he said, citing examples such as solar farms in the Philippines.
The growing return potential has led to higher willingness amongst allocators to invest in EMs. John Ball, chief executive officer of the Church of England Pensions Board echoed this view.
At a COP31 panel hosted by the UK’s emerging markets investor taskforce, Ball stressed, “the barrier is not the appetite”.
Perceived risk
In search for a solution to unlock capital flows, discussions in Antalya zeroed in on risk perception. Investors reckon EM transition assets are often judged to be high risk even though their fundamentals might not justify such perceptions.
“EMs continue to be penalised for the difference between perceived risk and real risk”, commented Amer Baig, CIO of the Green Climate Fund. “A lot of the concerns that investors have in EMs are the same ones they have in developed markets”, he added.
Inger Huus-Pedersen, senior portfolio manager at Danish pension investor PKA agreed. “‘EMs are perceived to be more risky than they actually are. It is not risk free to invest in developed markets anymore”, she said at a COP31 panel alongside Baig and Andreasen.
Baig and Huus-Pedersen’s views were hardly isolated opinions. Bertrand Millot, head of sustainability at Canadian asset owner La Caisse also raised a similar point.
“In EMs, we see great diversification potential. Their risks are not necessarily correlated with what’s happening in developed countries”, he said.
Examples were offered to back up their claims. PKA’s Huus-Pedersen said the fund was willing to take on local currency risk in EMs, citing diversification benefits. Singaporean sovereign wealth fund Temasek’s vice chairman for sustainability Steven Howard was confident renewable energy technology risks in EMs are low.
For pension investors, the appeal of emerging market transitions assets also extends to fiduciary duty. “This is not about us, this is about the generations to come”, said Church of England Pensions Board’s John Ball.
Ball’s comments came against the background of new regulatory guidance in the UK that has resurfaced debates over whether fiduciary duty should extend to systemic factors such as climate change.
Conversations in Antalya reflect a powerful trinity of tailwinds shaping investor confidence in EM transition assets: rising appetite, falling risk perceptions and systemic fiduciary obligations.